Wealth Management
Prime Assets
& Non-residents
Private banking partner selection
A bespoke structuring
LevCap advises investors seeking to acquire or refinance trophy assets in France. We analyse the patrimonial and financial situation, identify the most suitable banking institutions, and structure a file in compliance with the requirements of French and European banks regulated by the ACPR.
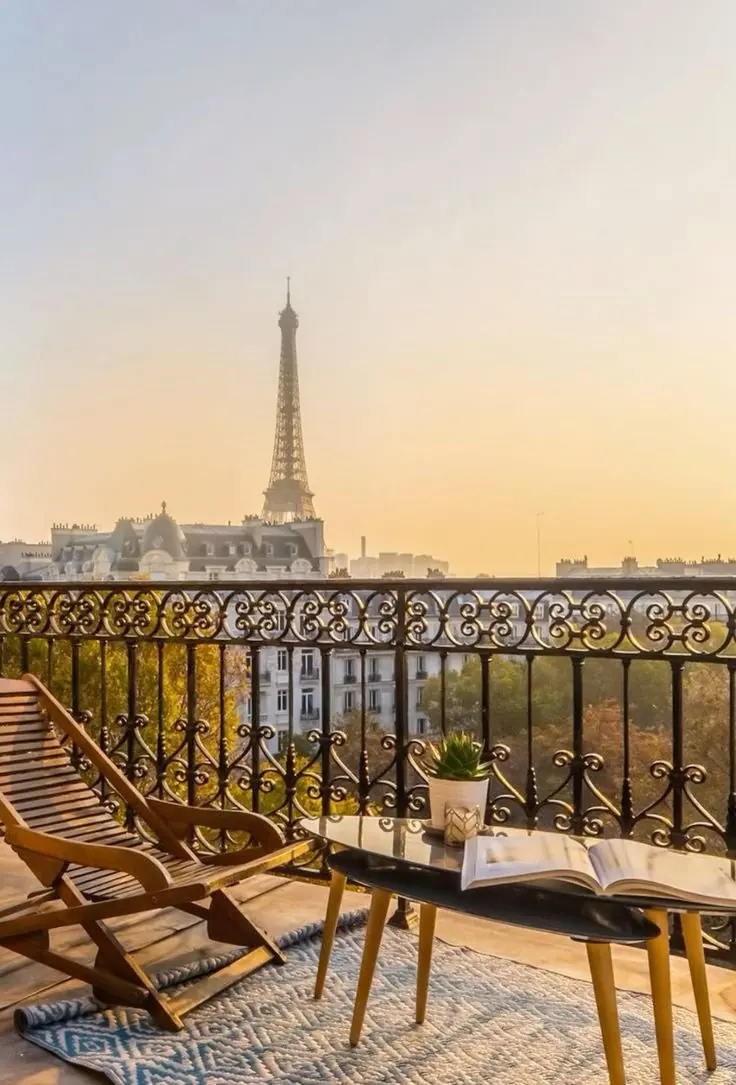
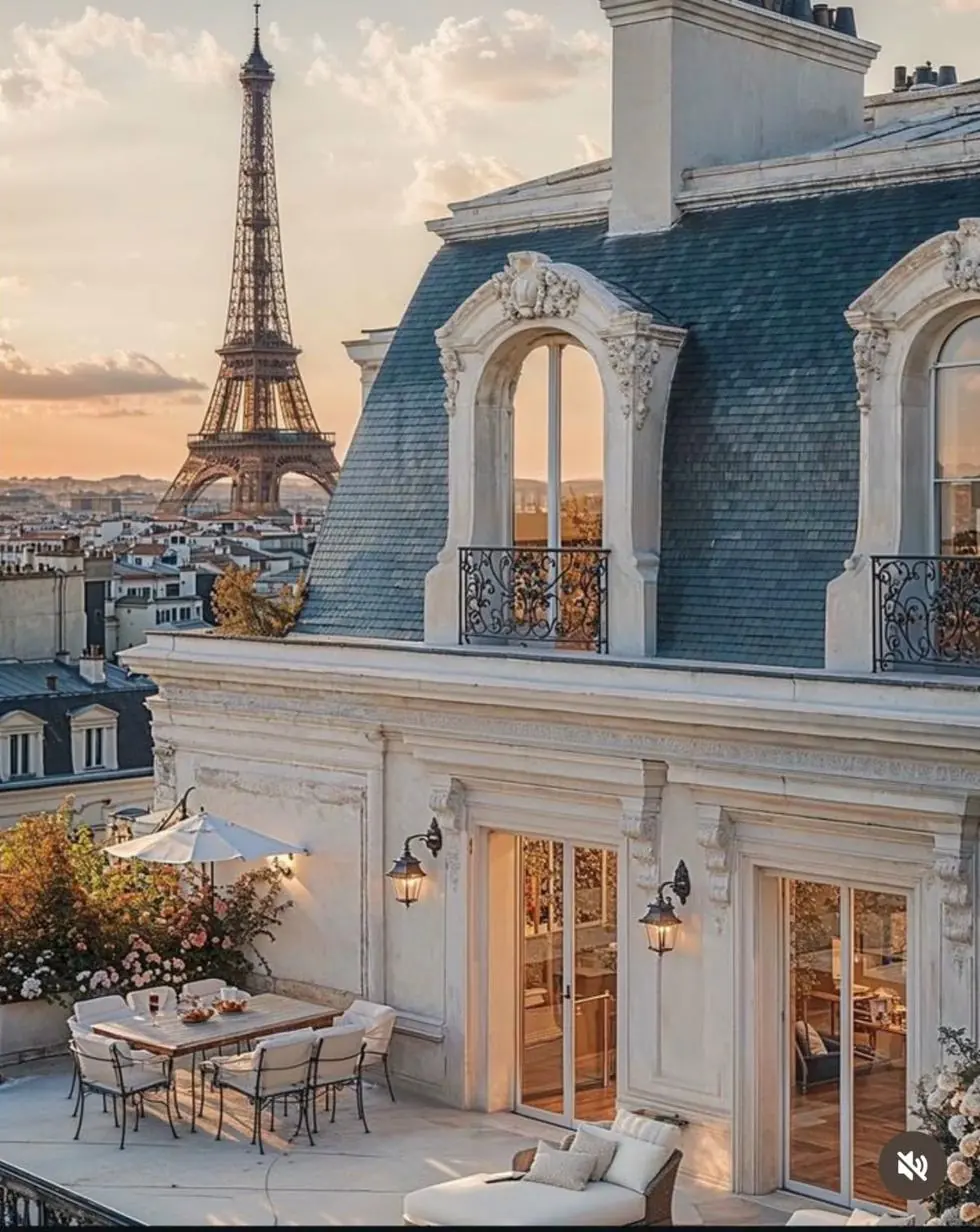
Paris · Eiffel Tower view
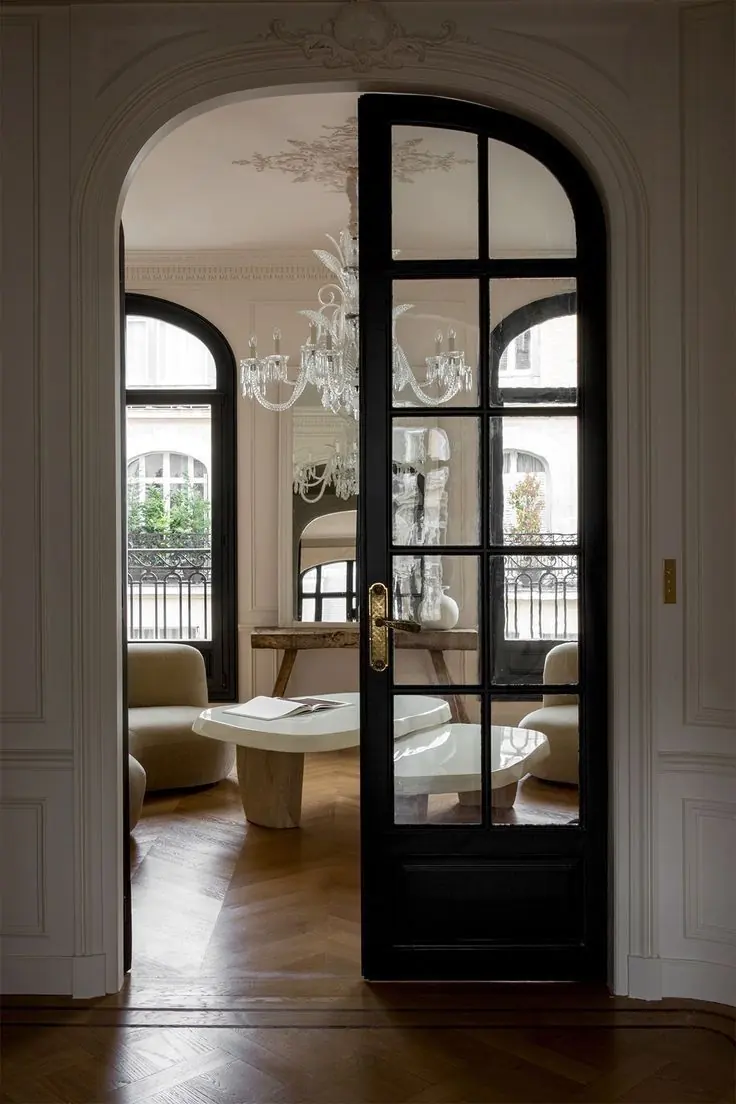
Paris · Trophy apartment
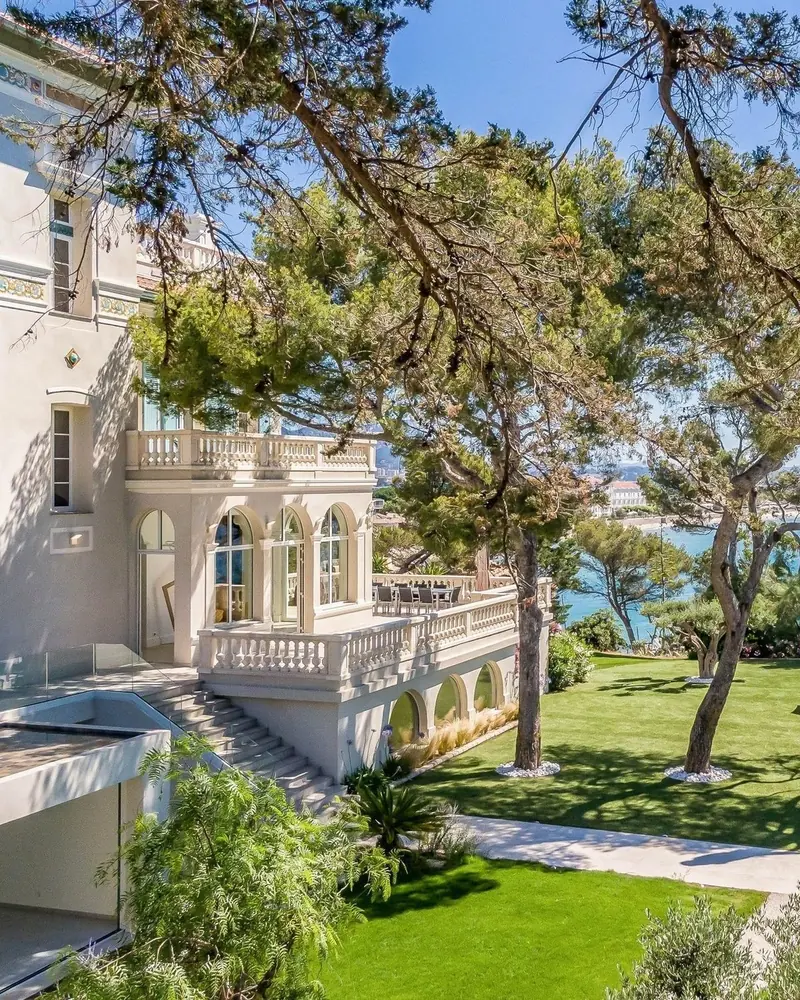
South of France · Sea-view villa
Non-resident specificities
Regulatory and documentary expertise
Acquiring real estate in France as a non-resident involves specific regulatory and documentary requirements. We carefully select the most relevant institutions based on the country of residence, the nature of income and the type of asset.
Comprehensive coordinated advisory
From identification to completion
Opportunity sourcing
Access to off-market and pre-selected assets
Architecture & Design
Introduction to leading architects
Legal & notarial advice
Coordination with notary firms and specialist practices
Tax optimisation
Tax benefit analysis and international coordination
Acquisition structure
SCI, bare ownership, holding — tailored to patrimonial profile
French banking
Opening French bank accounts for non-residents
Indicative tool
Loan amortisation simulator
⚠ Disclaimer — Please read carefully before any use
This simulator is provided by LevCap for strictly informational, illustrative and educational purposes only. It does not constitute a loan offer, a financing commitment, financial advice, tax advice, legal advice, or any investment recommendation within the meaning of MiFID II or any other applicable regulation.
Purpose of this tool: This simulator is solely intended to illustrate, in a simplified and generic manner, the mechanics of a loan amortisation schedule and the theoretical effect that leveraged financing may have on the taxable base of the French Wealth Tax (Impôt sur la Fortune Immobilière — IFI). It does not in any way prejudice a borrower's eligibility for credit, the actual terms of any financing, or anyone's effective tax position.
Important technical limitations: Results are based on deliberately simplified assumptions: fixed constant interest rate over the full term, straight-line amortisation with no deferred period, uniform annual appreciation of the asset, direct full ownership by an individual who is a French tax resident, and no other real estate assets or liabilities beyond those entered. These assumptions do not reflect the reality of structured financings or the complexity of individual wealth situations.
Regarding the IFI / Wealth Tax calculation: The indicative tax impact shown applies the 2026 IFI schedule (Art. 977 of the French General Tax Code) mechanically to a theoretical gross taxable base. This calculation does not account for: (i) the 30% principal residence allowance; (ii) other deductible liabilities beyond the loan entered; (iii) applicable international tax treaties; (iv) partial or total exemption regimes (business assets, SCPI, UCITS, etc.); (v) IFI capping rules; (vi) any usufruct or bare ownership structures; (vii) any other circumstances specific to your individual situation. This figure may not under any circumstances be used, cited, relied upon, or annexed to a tax return, notarial deed, or any other legally or patrimonially binding document.
LevCap is not a credit institution within the meaning of EU Regulation No. 575/2013, is registered with ORIAS as an intermediary in banking transactions and payment services (IOBSP) under no. 24006498, is not registered as a licensed investment adviser (CIF) with the AMF, and does not provide any regulated tax or wealth management advisory services. Any real estate financing or investment decision must be the subject of individual and personalised analysis by one or more qualified professionals: banker, ORIAS-registered credit broker, notary, tax lawyer, chartered accountant, or certified wealth management advisor (CGP/CGPI).